Fintech has more data than ever, so why are decisions still slow?
Fintechs have raced ahead of banks in adopting AI, but far fewer say it has changed how their business performs. The founder of an AI marketing start-up argues that the missing step is turning data into decisions.
Founder & CEO,
Plurio
Seva Ustinov is the founder and CEO of Plurio, a San Francisco-based martech start-up building an AI agent for performance marketing teams spending more than $500,000 a month on advertising. The views in this contributed piece are his own.
Fintech is significantly ahead of established financial institutions in terms of advanced adoption. According to the 2026 Global AI in Financial Services Report from the Cambridge Centre for Alternative Finance, 47 per cent of fintech companies are in advanced stages of AI implementation, compared to 30 per cent of banks. The gap is particularly noticeable at the stage of full-scale transformation: 19 per cent of fintech companies have reached this stage, compared to just 6 per cent in traditional finance. However, a high level of adoption does not mean that AI is actually changing this market: the same study shows that only 14 per cent of respondents believe AI has transformed their business and given them a competitive advantage. More than half of respondents admit that they find it difficult to measure the value of the AI tools they have already implemented.
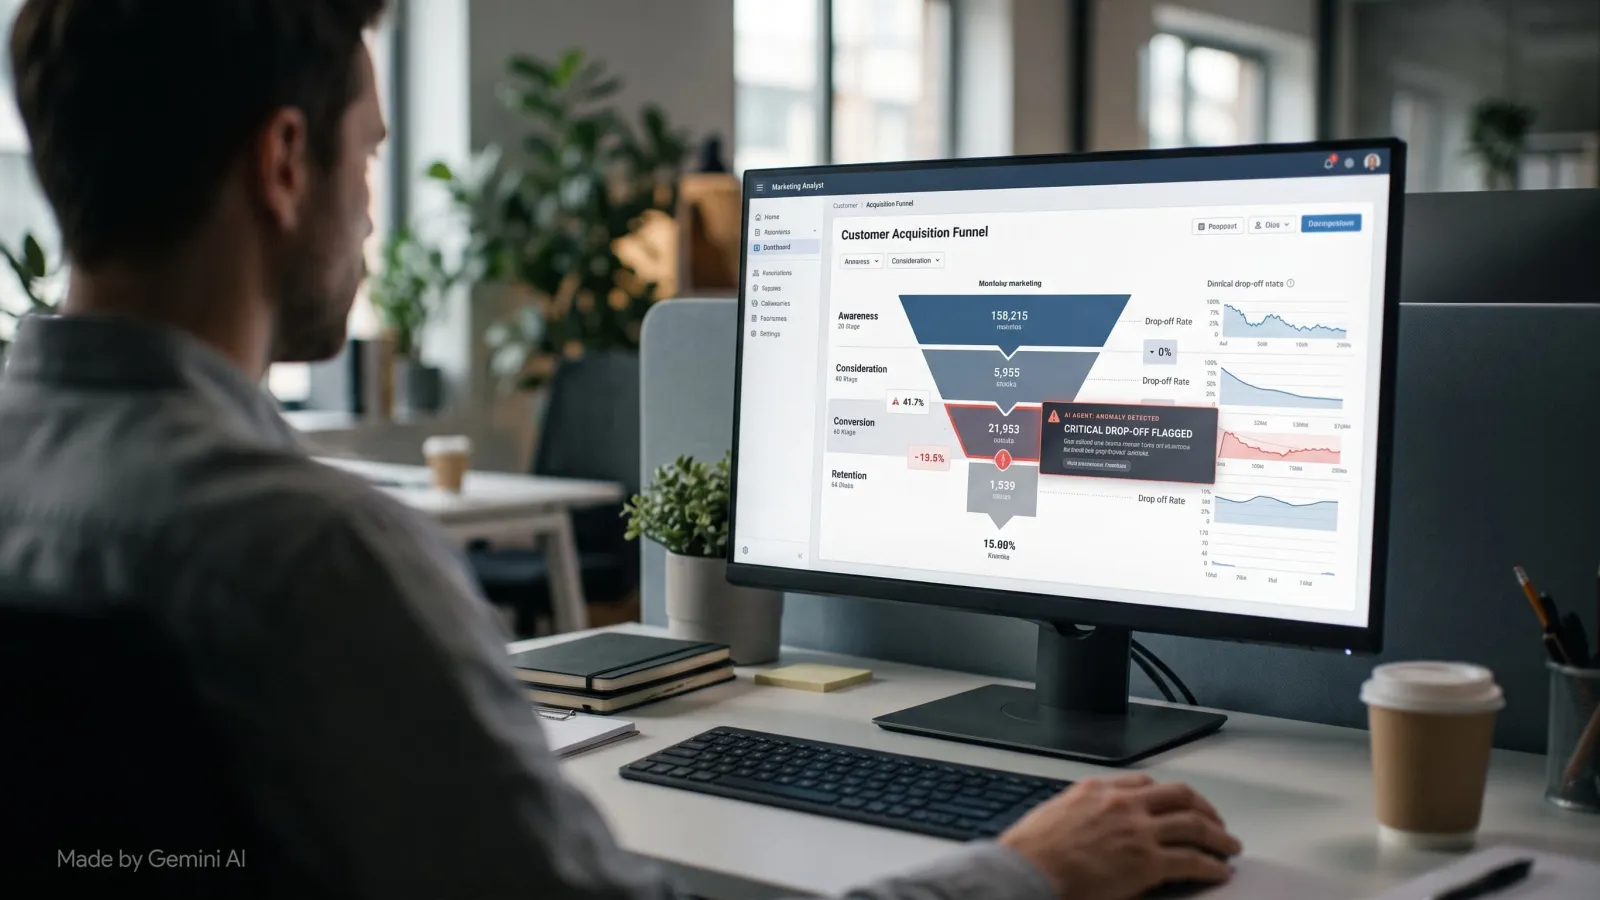
Fintech rarely uses AI in situations where decisions must be made that directly impact business results. Bots help automate and process information more quickly, visualise data, or write code. All of this, of course, saves time, but what should a company do with the information it receives? It’s one thing to have a system that shows in a matter of seconds that the cost of acquiring a customer (CAC) has risen by 15 per cent. It’s quite another to have a system that analyses where these customers came from, how many of them completed registration and KYC, how many opened an account, and how these metrics compare to the target CAC in a specific market. If the increase in cost is linked, for example, to a large influx of registrations that rarely result in opened accounts, the system will determine that the problem lies not in the volume of traffic but in its quality, and will suggest reallocating the budget toward channels that bring in more actual customers.
In my view, this is where the next phase of AI development in fintech is taking place. The next step is to teach AI to help people make decisions: to take multiple metrics into account at once, understand their impact on the business, and suggest specific actions. Obviously, this is much more complex than simply adding bots to an existing process.
Large amounts of data are starting to get in the way
A problem for companies that actively use data is that different analytics systems can show different aspects of the same process. For example, an advertising platform might show an increase in signups, analytics might show that the cost per acquisition has gone up, and the business’s own data might reveal a few days later that most of the users acquired never actually became customers. Each metric is accurate on its own, but if you look at only one of them, you might make a decision that improves only that metric, not the business outcome.
In fintech, a potential customer goes through several stages, from the initial interaction and registration to KYC and account opening. It is important for us to view the entire chain, rather than optimising each individual metric in isolation from the others. That is why the next stage in the development of data-driven fintech is the link that connects data from various sources with the business context, allowing us to assess not only what has already happened but also the likelihood of what will happen next.
How to avoid losing knowledge when employees leave
I think one of the most important reasons for implementing AI is the ability to turn a company’s accumulated experience into a functioning system. Imagine you have several specialists on your marketing team who have been with the company for a long time and know your specific business inside and out. They understand what should be scaled up, what kind of advertising is considered appropriate for a particular market, and which changes are best left untouched without additional data. When the team changes, some of this knowledge is inevitably lost.
An AI agent can help here. If the AI system stores a history of decisions and their outcomes, every action becomes a new source of information. Over time, this data will help make future decisions faster and more accurate. Agents can analyse account history, business metrics, and the context of different markets, and use the results of previous decisions to further refine workflows and rules.
In this way, the company will build up operational expertise. The more decisions that go through the agent and the better their outcomes are measured, the less the business depends on whether a particular employee remembers what worked last time.
The hardest part is not changing anything
When automating processes, we encounter another problem: AI should not react to every change in metrics. In performance marketing, for example, numbers are constantly changing, and not every change means you are on the brink of a crisis. Therefore, an AI agent must have clear conditions for taking action. For example, a change must persist for a certain period of time, exceed a set threshold, or be confirmed by multiple metrics. If these conditions are not met, the correct course of action is to continue monitoring.
This is especially important when working with advertising budgets. A system error that automatically changes the budget allocation costs the company money. Therefore, the autonomy of AI within a company must grow in tandem with the quality of oversight: the agent must understand not only what it can do, but also when it is best to stop and signal a human.
The next stage: decision-driven fintech
Fintech companies have learned to collect data on everything that happens with a customer, but simply having this information does not provide a competitive advantage. The advantage arises only when a company can quickly use that information to make decisions.
AI agents will become part of the fintech infrastructure, as they are capable of continuously analysing data, applying predefined business rules, and helping people make more decisions without having to manually process every signal.
I see the next step as building decision-driven companies, in which data continuously cycles through analysis, decision-making, execution, and evaluation of results. Each new result can then be used to refine the automations that will be applied next time. This creates a compounding effect: the system gradually improves its decision-making based on accumulated experience.
I am not saying that artificial intelligence will replace humans in decision-making. Rather, people will move into areas where human involvement adds the most value. Employees won’t need to manually check hundreds of ads or search for anomalies in spreadsheets every day. Their task will now be to determine which of the company’s business goals the AI system should pursue and where the acceptable limits lie.